
KNOW YOUR COVER: Essential Motor Insurance Facts for UAE Drivers
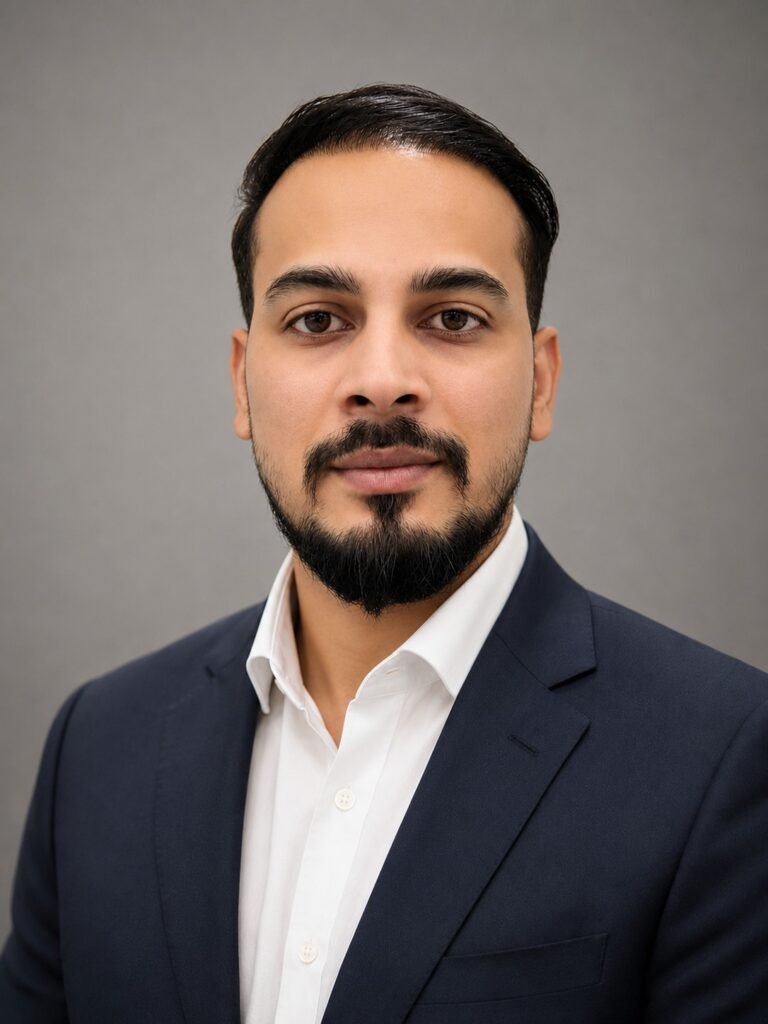
Mohammed Athar, Founder & CEO of GoCompare.ae, speaks exclusively with EmiratesReporter.com on key motor insurance matters every vehicle owner and driver in the UAE should understand. From the difference between third-party and comprehensive insurance to accident procedures, claim settlements, exclusions and choosing the right policy, the conversation highlights important points that can help motorists make more informed insurance decisions. Here is the conversation, presented as an awareness and knowledge resource for UAE residents and motorists, to help them better understand their motor insurance rights, responsibilities and coverage before they need to make a claim.
E.R- Is motor insurance compulsory in the UAE, and what does the law require every vehicle owner to have?
Mohammed Athar- Yes, Motor insurance is compulsory in the UAE, yet many customers face difficulties understanding what their policy actually covers. While third-party insurance meets the basic legal requirement, customers are sometimes surprised to learn that damage to their own vehicle is not covered. This can create unexpected financial burdens, particularly when motorists assume that having valid insurance means all accident-related expenses will be paid.
Customers may also face confusion over policy exclusions, repair costs, deductibles and claim settlements. Before purchasing insurance, motorists should clearly understand the difference between third-party and comprehensive cover, check the benefits and exclusions, and choose a policy that meets their needs rather than focusing only on the lowest premium. Clear guidance from insurers and brokers can help customers make informed decisions and avoid unpleasant surprises during claims.
Driving without valid motor insurance in the UAE is a traffic violation. The published penalty for driving without insurance is AED 500, four black points and vehicle impoundment for seven days. Motor insurance is also required for vehicle registration and renewal.
E.R- What is the real difference between third-party liability insurance and comprehensive motor insurance?
Mohammed Athar- Third-party insurance covers the insured driver’s legal liability for injury, death or property damage caused to others in an accident, but it does not ordinarily cover damage to their own vehicle.
Comprehensive insurance includes third-party liability cover and can also cover accidental damage to the insured vehicle, subject to policy terms, exclusions and deductibles. Additional benefits, such as agency repairs, roadside assistance and replacement vehicles, vary between insurers. Motorists should compare coverage and benefits, not just the premium.
E.R- If a driver causes an accident, who pays for damage to vehicles, medical expenses and other losses?
Mohammed Athar- If a driver causes an accident, their insurer generally covers eligible damage to other vehicles and third-party property, as well as compensation for injury or death, subject to UAE law and the applicable policy. The amount payable depends on the established liability, supporting evidence and relevant coverage terms.
Damage to the at-fault driver’s own vehicle is not covered by third-party insurance but covered under a comprehensive policy, subject to its terms, exclusions and deductible. Motorists should remember that not every expense is automatically covered, so understanding their policy and following the proper accident-reporting process is essential.
Illustrative Image
E.R- What should a motorist do immediately after a road accident in the UAE to protect their legal rights and insurance claim?
Mohammed Athar- After a road accident in the UAE, prioritize safety and call 999 for police assistance or 998 for an ambulance if needed. Report the accident through the appropriate official channel and obtain the accident report required for your insurance claim.
Where safe, take photos of the damage, exchange details with the other driver and notify your insurer or broker promptly. Avoid unauthorized repairs or private settlements, and keep all relevant documents and receipts. Following these steps can help protect your legal rights and support a smoother claims process.
Common mistakes that can delay or jeopardise a motor insurance claim include failing to report the accident through the proper official channels, delaying notification to the insurer, providing incomplete or inaccurate information, and not submitting the required documents. Authorising repairs before obtaining the necessary approval or accepting a private settlement without understanding the consequences can also create complications.
E.R- Why do insurance companies sometimes reject claims or pay less than motorists expect?
Mohammed Athar- Motor insurance claims may be rejected or settled for less than expected due to policy exclusions, incorrect information, breaches of policy conditions, disputes over accident liability or differences in vehicle repair costs and valuation.
Motorists should understand that comprehensive insurance does not cover every type of damage, and deductibles, coverage limits and applicable policy terms may affect the settlement.
If a claim is rejected or the offer seems insufficient, motorists should request a written explanation from the insurer, review the policy terms and challenge any errors through the insurer’s complaints process or the applicable UAE insurance dispute-resolution channels.
Common reasons for rejected or reduced motor insurance claims in the UAE include policy exclusions, incorrect information, missing documents, unauthorised vehicle modifications, and driving without a valid licence or under the influence of alcohol or drugs. Mechanical failures and wear and tear are also generally excluded from accidental damage cover. The outcome depends on the policy terms, applicable law and circumstances of the claim.
E.R- Does comprehensive insurance mean that every type of damage to a vehicle is covered?
Mohammed Athar- No. Comprehensive motor insurance does not cover every type of damage. Coverage depends on the policy terms, exclusions, deductibles and limits. For example, wear and tear and mechanical failures are generally not covered as accidental damage, while benefits such as agency repairs, flood damage and roadside assistance may vary by policy.
Motorists should carefully review the policy wording, check what is included and excluded, and clarify any uncertainties with their insurer or broker before purchasing. This helps avoid unexpected costs or misunderstandings when making a claim.
E.R- How should motorists choose the right insurance policy rather than simply buying the cheapest one? How can they compare policies and make an informed decision?
Mohammed Athar- Motorists should compare motor insurance policies based on coverage, benefits and claims service, rather than choosing solely on price. Important factors include policy exclusions, deductibles, additional benefits, vehicle valuation and the level of protection provided.
Repair arrangements are also important. Some insurance companies offer agency repairs, while others use approved garage networks. The available garages, repair quality, vehicle eligibility and repair terms can differ between insurers, so customers should check these details before purchasing.
When comparing quotations, motorists should ensure that the coverage, deductibles and benefits are similar. An insurance comparison platform or broker can help explain these differences and identify a policy that suits the vehicle owner’s needs and budget. Ultimately, the best choice is a policy that offers appropriate protection, reliable claims support and clear repair arrangements at a reasonable price.
Illustrative Image
E.R- What are the most important motor insurance rights and responsibilities that every UAE driver should know?
Mohammed Athar- Every UAE motorist should understand their insurance rights and responsibilities. Customers have the right to understand their policy coverage, exclusions and deductibles, submit eligible claims, receive an assessment in line with applicable rules, and raise complaints through the appropriate channels if a dispute remains unresolved.
Drivers are responsible for maintaining valid insurance, providing accurate vehicle and driver information, holding the required driving license, and following UAE traffic laws. After an accident, they should report it through the appropriate official channel, notify their insurer promptly and provide the necessary documents.
Before purchasing a policy, motorists should review the coverage, exclusions, repair arrangements and claim conditions. Understanding these responsibilities and keeping the policy details accurate can help prevent unexpected costs and reduce delays or disputes during the claims process.
Ultimately, informed motorists should know what they have purchased, how to use their coverage and what steps to take if an accident occurs. Understanding these responsibilities before a claim arises can help prevent avoidable disputes and delays.
About Mohammed Athar, Founder & CEO | GoCompare.ae :
Mohammed Athar built his career from the ground up in the insurance industry, developing extensive knowledge of insurance products, market dynamics, and industry operations. Through years of hands-on experience and a deep understanding of customer needs, he founded GoCompare.ae, a UAE-based insurance aggregator that combines market expertise, technology, and a service-driven approach to simplify insurance and deliver a better customer experience.
- AS TOLD TO EMIRATESREPORTER.COM. THE VIEWS EXPRESSED ARE SOLELY THOSE OF THE GUEST/INTERVIEWEE.
- Your Skills, Our Spotlight. Email editor@emiratesreporter.com to Get Featured.